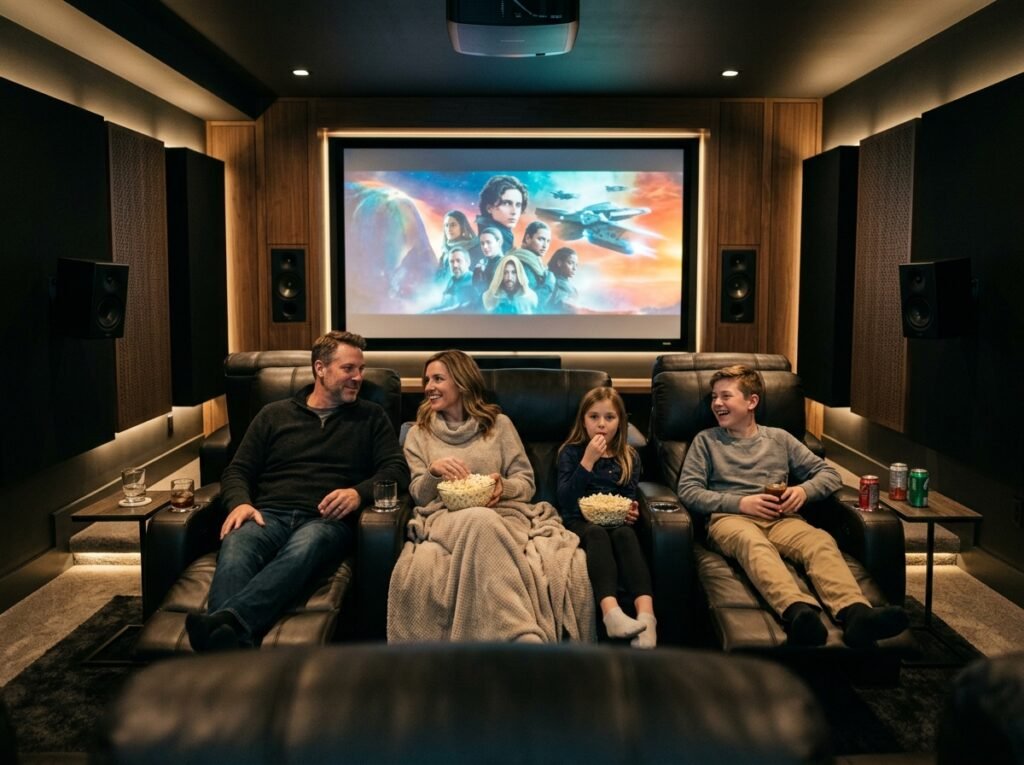
Home Theater Maryland Build the Room First. The Equipment Will Follow.
Most Maryland homeowners planning a basement home theater make the same mistake: they start with the equipment.
They pick a projector, choose a sound system, look at seating options and then try to fit everything into a basement that was never designed for any of it. The result is a room that looks expensive but performs poorly echo off bare drywall, light bleed from an improperly sealed ceiling, bass frequencies that boom through the floor upstairs, and a seating arrangement that puts half the viewers at the wrong angle.
A home theater is a room before it is a technology installation. The room determines the acoustics. The room determines the isolation. The room determines the sight lines, the screen size, the projector throw and the seating configuration. Get the room wrong and the best equipment on the market will underperform. Get the room right and even a mid-range system will deliver an experience that rivals commercial cinemas.
At Fortune Homes MD, we build home theater rooms from the foundation up soundproofing, acoustic treatment, lighting, electrical, HVAC, framing and all finishes before the first piece of AV equipment is installed. One construction crew. One scope. One Maryland-permitted result that performs the way a home theater is supposed to.
We serve: Baltimore County · Montgomery County · Howard County · Prince George’s County · Anne Arundel County · Frederick County · Carroll County
📞 Call Now: (410) 413-0739 | 📧 Email: info@fortunehomesmd.com
Maryland Rental Investment Benchmarks What Good Looks Like by Market
County / Market | Target CoC | Target GRM | Cap Rate | 5-Yr IRR Target | Investment Strategy |
Baltimore City | 8%–14% | 7–12 | 8%–11% | 12%–18% | Cash flow + value-add | Highest yield market | Active management required |
Baltimore County | 5%–9% | 11–15 | 7%–9% | 10%–14% | Cash flow + moderate appreciation | Family tenant pool | Good LTV economics |
Montgomery County | 3%–6% | 16–22 | 5%–7% | 13%–19% | Appreciation-driven | Thin year-one cash flow | High IRR from appreciation over 7+ year hold |
Howard County | 4%–7% | 14–18 | 6%–8% | 11%–16% | Appreciation + quality cash flow | Columbia school zone premium | WSSC cost factor |
Prince George’s County | 6%–10% | 11–15 | 7%–9% | 11%–15% | Cash flow + Metro-area appreciation | Active rental market | WSSC cost factor |
Anne Arundel County | 5%–8% | 12–16 | 6%–8.5% | 10%–14% | Military/federal tenant stability | Moderate appreciation | Good rental market fundamentals |
Frederick County | 6%–9% | 12–16 | 7%–9% | 10%–14% | Growth market | Baltimore/DC commuter demand | BTR opportunity | Lower land cost |
Carroll County | 7%–11% | 9–13 | 8%–11% | 11%–15% | Cash flow focus | Simplest regulatory environment | Smallest tenant pool | Rural character |
Source: Fortune Homes MD investment analysis data; Maryland MLS cap rate data; Zillow/Rentometer Maryland rental market Q1 2026; Maryland SDAT property assessment data.
🔶 Know Your Maryland Market Benchmarks Before You Buy
All 6 metrics. County-specific benchmarks. MHIC licensed investor support.
📞 (410) 413-0739
📧 info@fortunehomesmd.com
→ Cash-on-Cash Return | → NOI Analysis | → Break-Even Analysis
CTA — Start With a Financing Strategy Consultation
Conventional mortgages — loans underwritten to Fannie Mae or Freddie Mac guidelines — are the most familiar loan type and often offer the lowest interest rates available for investment property. They are also the most documentation-intensive and carry the most structural restrictions for serious portfolio investors.
How conventional investment loans work:
Conventional investment property loans are underwritten based on your personal income, credit history, debt-to-income ratio, and reserves. The lender verifies two years of employment or self-employment history, tax returns, bank statements, and all existing debt obligations. The property’s rental income potential may factor into qualification, but personal income is the primary underwriting foundation.
Current conventional investment property requirements (2026):
- Minimum credit score: 620 for basic eligibility; 680+ for investment properties is commonly required; 740+ for best rates
- Minimum down payment: 15% for single-unit investment properties; 25% for 2–4 unit properties (Fannie Mae eligibility matrix)
- Debt-to-income ratio: Maximum 45% DTI
- Cash reserves: 6 months PITIA post-closing typically required
- Property count limit: Maximum 10 financed properties (Fannie Mae conventional guidelines)
- Rate premium: Investment property rates typically run 0.5–0.75% above primary residence rates
The house-hacking exception:
One powerful application of conventional lending for new investors is house-hacking — buying a 2–4 unit multifamily property, occupying one unit, and renting the others. Fannie Mae’s updated guidelines (effective November 2023) allow down payments as low as 5% for owner-occupied 2–4 unit properties under the HomeReady program. Loan limits are $929,850 for duplexes, $1,123,900 for triplexes, and $1,396,900 for fourplexes. This structure allows investors to generate rental income while qualifying for owner-occupied loan terms — a meaningful capital efficiency tool for first-time investors entering markets like Glen Burnie, Dundalk, or Essex where 2–4 unit inventory exists at accessible price points.
Who conventional loans work best for:
Investors with strong W-2 income, clean tax returns, fewer than 10 financed properties, and the ability to document a clear debt-to-income picture. Investors who are self-employed, have complex income structures, are approaching the 10-property limit, or need to close fast will often find conventional underwriting more limiting than its rates suggest.
The DSCR loan is the cornerstone of modern rental portfolio financing. It qualifies based on the property’s rental income relative to its debt service — with no requirement for personal tax returns, W-2s, employment verification, or DTI analysis. For self-employed investors, portfolio-focused landlords, and anyone who has hit Fannie Mae’s conventional ceiling, DSCR is the most important financing product in the market today.
How DSCR qualification works:
DSCR = Monthly Gross Rental Income ÷ Monthly PITIA (Principal, Interest, Taxes, Insurance, and HOA if applicable)
A ratio of 1.0 means the property breaks even on debt service. A ratio of 1.25 means income covers debt by 25% — the target for best-rate qualification at most Maryland lenders. Programs are available down to 0.75 with pricing or LTV adjustments. “No Ratio” DSCR products exist for properties without established rental history, typically with a 25% down payment.
DSCR loan benchmarks in Maryland (Q1 2026):
- Rates: Approximately 5.875%–7.375% for qualified borrowers — down meaningfully from the 8–9% range seen throughout much of 2024
- Best-rate profile: 720+ FICO, 1.25+ DSCR, 25%+ down payment
- Minimum FICO: 640 (some programs accept 600)
- Down payment: 20% minimum
- LTV: Up to 80%
- Loan amounts: $100,000–$3,000,000+
- Cash reserves required: 3–6 months PITIA post-closing
- No limit on number of financed properties
- LLC and entity ownership fully supported
- Closing timeline: 15–34 days
Why DSCR works in Maryland’s rental market:
Maryland’s rental fundamentals make DSCR qualification achievable across a wide range of markets. In affordable acquisition markets like Baltimore City — where median home prices sit around $217,000 and average rents range from $928 for studios to $1,292 for two-bedrooms — the low acquisition price creates a favorable DSCR spread. In higher-rent markets like Bethesda and Rockville, where two-bedroom rents regularly exceed $2,500/month, DSCR qualification is supported by income levels that comfortably cover debt service even at premium acquisition prices.
In Dundalk, where rents average $2,100–$2,300/month against median acquisition prices around $240,000, the DSCR math is compelling. In Germantown, where 41% of housing stock is attached rowhomes with rents that track the county’s broad government and life sciences employment base, DSCR financing allows portfolio expansion without conventional income documentation constraints.
DSCR and Maryland’s rent stabilization environment:
When using DSCR for properties subject to rent stabilization, income projections must reflect regulatory limits. Montgomery County’s Rent Stabilization Law (Bill 15-23) caps annual increases at CPI-U + 3%, maximum 6%, with the 2025–2026 allowable increase set at 5.7%. Prince George’s County’s PRSA applies to pre-2000 construction. Properties built after 2000 in both counties are exempt from stabilization — a critical DSCR qualification advantage for newer inventory in markets like Bowie and Largo. Anne Arundel County and Frederick County carry no rent stabilization at all, making income projections fully market-driven for DSCR calculation.
For a detailed breakdown of DSCR loans for Maryland rental investors, see our dedicated Private Lending page.
Some community banks, credit unions, and regional lenders hold loans in their own portfolio rather than selling them to Fannie Mae or Freddie Mac. Because these loans stay on the lender’s balance sheet, they don’t need to conform to agency guidelines — which means more flexibility on documentation, property type, property count, and loan structure.
Portfolio loans are particularly valuable for investors who have strong banking relationships, hold unusual property types, or need terms that fall outside the Fannie Mae box. They’re also a viable path for investors who have exceeded the 10-property conventional limit but aren’t yet ready to transition fully to DSCR lending.
Typical portfolio loan characteristics:
- Rates: Generally competitive with conventional but may carry a slight premium for flexibility
- Down payment: Typically 20–30%
- Documentation: More flexible than agency guidelines — can sometimes accommodate irregular income, shorter employment history, or unusual property configurations
- Property count: No agency-imposed limit; lender’s own risk appetite governs
- Loan size: Varies widely by lender; strong relationship helps
Maryland’s dense community banking network — particularly in markets like Annapolis, Bethesda, and Frederick — makes portfolio lending a viable conversation for investors with established relationships and stable assets.
Conventional, DSCR, or portfolio — the right answer depends on your situation. Fortune Homes MD helps you find it. Get Your Free Financing Assessment →
FHA loans are government-backed mortgages administered by the Federal Housing Administration. They require the borrower to occupy the property as a primary residence — which makes them a limited but powerful tool for new rental investors willing to live in one unit of a 2–4 unit property.
FHA investment property basics:
- Minimum down payment: 3.5% (with 580+ credit score); 10% (with 500–579 credit score)
- Maximum units: 4 (borrower must occupy one unit)
- Occupancy requirement: Minimum 1 year in the property
- No property count restrictions for future FHA loans, but only one FHA loan at a time
Why FHA matters for Maryland investors:
FHA’s minimum down payment of 3.5% dramatically lowers the capital barrier to entry for a first rental investment. An investor buying a $350,000 duplex in Glen Burnie can close with as little as $12,250 down — while collecting rent on the second unit. After one year in occupancy, the property can be converted to a full investment property, and the investor can repeat the process.
FHA loan limits in Maryland vary by county. High-cost counties — Montgomery, Howard, Frederick, Prince George’s, Anne Arundel, and Baltimore County — all carry elevated FHA limits that accommodate the state’s premium market values. Frederick County’s 2026 FHA loan limit of $1,249,125 (the highest tier, matching Montgomery County) is a notable marker of the federal government’s recognition of local market pricing.
Limitations to know: FHA comes with mortgage insurance premiums (MIP) — both upfront and ongoing — that add to the total cost of financing. The occupancy requirement means it only works as an investment entry strategy, not a portfolio scaling tool. And property condition standards are stricter than for conventional investment loans — properties must meet FHA minimum property standards.
Veterans, active-duty service members, and surviving spouses eligible for VA loan benefits can apply VA financing to multifamily properties of up to four units — with zero down payment — provided they occupy one unit. This is among the most powerful capital-efficient paths into rental investment available in the U.S. market.
Maryland’s significant military presence — Fort Meade in Anne Arundel County with over 62,000 jobs, Fort Detrick in Frederick County serving five cabinet-level agencies with approximately 10,000 personnel, and Aberdeen Proving Ground — means a substantial portion of Maryland’s investor pool has access to VA eligibility.
VA multifamily investment basics:
- Down payment: $0 (for eligible borrowers within the VA loan limit)
- Units: Up to 4 (borrower must occupy one unit)
- Mortgage insurance: None (VA funding fee instead, which can be financed)
- Rate: Generally competitive with or below conventional investment rates
- Property condition: Must meet VA minimum property requirements
A veteran buying a $400,000 triplex in Pasadena can close with no down payment, collect rent on two units, and build a rental track record that sets up future investment financing with documented income history. This is a fundamentally different capital equation than any other financing path available.
For investors who already own a property with significant equity — whether a primary residence or an existing rental — a HELOC or home equity loan provides access to that equity as a source of down payment or acquisition capital for the next investment.
HELOC basics for Maryland investors:
- How it works: A revolving line of credit secured by property equity — borrow as needed up to the limit during the draw period (typically 10 years), repay during the repayment period (typically 10–20 years)
- Borrowing capacity: Up to 75–80% of property value, minus existing mortgage balance
- Rates: Investment property HELOCs average 7.5–9.5% APR in 2026; primary residence HELOCs average 8.05–8.28% — the premium for investment property HELOCs runs approximately 0.5–1% above primary residence rates
- Variable rate risk: HELOC rates are tied to the prime rate and will adjust as the market moves
- Tax consideration: Interest may be deductible when used to “buy, build, or substantially improve” the property securing the loan — consult a tax advisor
Home equity loan alternative: A home equity loan provides a lump sum at a fixed rate rather than a revolving line. This is better suited when you have a specific, known acquisition cost rather than ongoing capital needs. Primary residence home equity loan rates averaged 8.28% in 2025; investment property home equity loans typically ran 0.5–1% higher.
The waterfall strategy:
One of the most effective approaches for scaling a Maryland rental portfolio is what portfolio builders call the “waterfall technique” — using cash flow and equity from existing rentals to fund down payments on future properties. A HELOC on an existing rental with significant appreciation is a direct implementation of this strategy. Maryland’s strong appreciation trajectory in markets like Urbana (31.8% YoY in recent data), College Park (40.3% price per square foot appreciation), and Bethesda (11% YoY) has produced substantial equity positions for long-term holders that can now be recycled into new acquisitions.
Qualifying requirements: Investment property HELOCs are harder to obtain than primary residence HELOCs. Lenders typically require 25–30% equity in the property, a credit score of 680+, 6 months of cash reserves, and documentation of the property’s rental income. Fewer lenders offer this product compared to primary residence HELOCs, so working with a lender familiar with investor-focused HELOC programs is important.
A cash-out refinance replaces an existing mortgage on a property with a new, larger loan — the difference between the old balance and the new loan amount is paid to the borrower in cash. For investors with appreciated rentals or primary residences, a cash-out refinance is one of the most straightforward ways to access equity for a new investment acquisition.
How it works in practice:
Suppose an investor owns a rental in Towson purchased at $350,000 in 2021, now appraised at $480,000, with a remaining mortgage balance of $280,000. A cash-out refinance at 75% LTV would produce a new loan of $360,000 — paying off the existing $280,000 balance and delivering $80,000 in cash proceeds. That $80,000 can fund the down payment on the next acquisition.
Cash-out refinance considerations:
- Must maintain sufficient equity post-refinance (typically 25% LTV or less)
- New loan resets amortization clock — evaluate impact on long-term interest costs
- DSCR cash-out refinances available as early as 6 months after acquisition (minimum seasoning)
- For existing DSCR loans, cash-out refi up to 75% LTV with no income documentation required
- Primary residence cash-out refi: up to 80% LTV; investment property: up to 75% LTV at most lenders
Cash-out refinancing of DSCR loans is one of the most underutilized tools in Maryland rental portfolio building. Many investors don’t realize they can extract equity from a stabilized rental through a DSCR cash-out without any income documentation — simply based on the property’s value and its rental income coverage ratio.
Once an investor accumulates three or more rental properties, managing separate financing on each becomes both administratively burdensome and strategically limiting. Blanket loans — also called portfolio loans in the multi-property context — consolidate multiple properties under a single loan structure, simplifying debt management and often improving overall terms.
How blanket loans work:
- Multiple properties serve as collateral for a single loan
- One monthly payment replaces multiple individual mortgage payments
- Underwriting evaluates the portfolio’s combined income and cash flow
- Often structured as commercial loans with 5–10 year terms and 20–25 year amortization
- Available for 5+ unit portfolios or 5+ individual properties
For Maryland investors who have built portfolios spread across multiple counties — for example, a mix of Baltimore City rowhomes, Dundalk single-families, and Columbia townhomes — a blanket loan consolidates the debt structure while potentially improving the blended DSCR by offsetting weaker individual properties with stronger performers in the portfolio.
Conventional lending caps at 10 financed properties. DSCR lending has no such limit. But for investors managing 10–30+ properties, a blanket or portfolio loan structure can be more efficient than running 30 separate DSCR loans with 30 separate insurance policies, tax escrows, and payment management obligations.
Whether you own one property or twenty, Fortune Homes MD helps you structure the right debt across your full portfolio. Schedule Your Portfolio Financing Consultation →
In seller financing, the property seller acts as the lender — carrying the mortgage rather than receiving a cash lump sum at closing. The buyer makes payments directly to the seller according to a negotiated note. Terms are fully flexible and set by agreement between the parties.
Seller financing is most relevant when a seller owns a property free-and-clear (or nearly so), when conventional financing is unavailable due to property condition, and when the seller has capital gains tax motivation to spread proceeds over time rather than receiving a lump sum in a single tax year.
When seller financing works in Maryland:
Distressed or deferred-maintenance properties that don’t meet conventional lender condition standards are natural candidates for seller financing — the seller may be motivated to close without requiring the buyer to secure traditional financing. Older sellers with significant equity who want income without managing the property are another natural fit.
From a tax perspective, seller financing allows the seller to report gains using the installment method — spreading the recognition of capital gains across the life of the note — which can be more advantageous than a 1031 exchange in some situations.
Key considerations: Seller financing requires negotiating a promissory note and deed of trust (or mortgage) directly with the seller. Interest rates, down payment, amortization schedule, and balloon payment terms are all negotiable. Maryland has no usury laws that cap rates on investment property seller financing. Both parties should engage legal counsel to structure the transaction properly.
The 1031 exchange is not a loan product — it’s a tax deferral mechanism that allows an investor to sell one investment property and reinvest the proceeds into a new “like-kind” property without paying capital gains tax on the sale. There is no cap on how many times you can execute a 1031 exchange, and there is no restriction on property type — you can exchange a single-family rental for a duplex, a duplex for a small commercial building, or a residential portfolio for a multifamily property.
The 1031 process:
- Sell the relinquished property and identify a Qualified Intermediary (QI) to hold funds
- Identify the replacement property within 45 days of the sale
- Close on the replacement property within 180 days of the sale
- The replacement property must be of equal or greater value than the relinquished property
- Report the exchange on IRS Form 8824
Why 1031 matters for Maryland investors:
In Maryland markets that have seen significant appreciation — Urbana, Silver Spring, College Park, Bethesda — long-term rental holders may have accumulated substantial capital gains that would be heavily taxed in a conventional sale. A 1031 exchange allows those gains to be recycled into a better-positioned property or a larger asset class without triggering immediate tax liability.
A Maryland investor who purchased a Baltimore City rowhome for $130,000 in 2015 and has seen appreciation to $260,000+ can sell and move the entire proceeds into a larger asset — a duplex, small apartment building, or a higher-rent suburban property — deferring all capital gains along the way. The deferred gain follows the new property until it is eventually sold in a taxable transaction (or the investor’s estate steps up the basis at death, potentially eliminating the deferred gain entirely under current law).
Important: 1031 exchanges are complex and time-sensitive. Engaging a qualified tax advisor and a reputable QI before listing the relinquished property is essential.
Choosing the Right Financing for Your Maryland Rental Investment
No single financing product is right for every investor or every deal. The right choice depends on your income profile, your existing portfolio, your target market, and your investment timeline. Here’s a practical decision framework.
If you have strong W-2 income and fewer than 10 financed properties: Start with conventional financing for the lowest available rates. Use FHA or VA for an initial house-hack if you’re willing to occupy one unit. Plan your transition to DSCR before you hit the 10-property ceiling.
If you are self-employed or have complex income: DSCR is likely your primary path from the outset. No W-2, no tax returns, no DTI — qualify based on the property’s income. Work with a lender who understands Maryland’s market and can advise on DSCR structure for each acquisition.
If you own existing properties with significant equity: Consider a HELOC or cash-out DSCR refinance to access equity for the next acquisition without touching personal savings. The “waterfall” approach — recycling rental income and equity into new down payments — is how serious Maryland portfolio builders scale without constant fresh capital injection.
If you are a veteran or active-duty service member: Explore VA multifamily financing for your first acquisition. Zero down, no mortgage insurance, and income from rented units to support your primary residence payment is a uniquely powerful starting point that civilian investors cannot access.
If you are building a larger portfolio (10+ properties): DSCR with no property count limit is your primary tool. At 20–30+ properties, evaluate whether a blanket/portfolio loan structure simplifies your debt management. Revisit your portfolio annually to identify properties that have appreciated sufficiently to support a cash-out DSCR refinance.
If you are selling an appreciated Maryland rental: Before listing, consult a tax advisor about a 1031 exchange to defer capital gains and redeploy full equity into a larger or better-positioned asset.
Maryland Market Context: How Financing Fits Each County
Financing choices should reflect the specific dynamics of each Maryland market you are entering.
Baltimore City — Low acquisition prices ($150,000–$250,000 range for rowhomes), strong cash flow potential at current rents, no rent stabilization. DSCR is often the most efficient tool here, especially for LLC-held portfolios. House-hacking with FHA is viable in select neighborhoods with 2–4 unit inventory.
Baltimore County — Dundalk and Essex offer affordable entry points with favorable DSCR math. Towson and Catonsville serve higher-income tenant profiles at higher price points where conventional financing may still compete on rate.
Montgomery County — The Rent Stabilization Law (5.7% cap for 2025–2026) affects income projections for pre-2000 stock. Post-2000 construction is exempt. DSCR income calculations should reflect current stabilized rents, not theoretical market upside. Germantown and Gaithersburg offer the most favorable entry-price DSCR dynamics in the county.
Howard County — Second-highest-earning county in the U.S. Columbia‘s homeowners’ association (CA) fees affect DSCR calculations — factor HOA into PITIA before qualifying. Strong tenant quality and low vacancy support stable income projections.
Prince George’s County — PRSA rent stabilization applies to pre-2000 units. Build-to-rent new construction is exempt, creating a strategic new construction investment angle with uncapped rent upside. Bowie and College Park are among the strongest appreciation markets in the county.
Anne Arundel County — No rent stabilization. Fort Meade’s 62,000 jobs anchor military tenant demand across multiple submarkets. Annapolis waterfront properties command premium STR income — DSCR with STR income documentation is applicable in the right locations.
Frederick County — No rent stabilization. The 2026 FHA loan limit of $1,249,125 signals the county’s premium federal market classification. Fort Detrick PCS rotation creates consistent government rental demand for investors in the City of Frederick and surrounding communities.
Common Questions Maryland Investors Ask About Rental Financing
For a conventional investment property loan: 15% for a single-unit property; 25% for a 2–4 unit investment property. For DSCR loans: 20% minimum. For FHA with owner-occupancy of one unit: 3.5% (with 580+ credit). For VA with owner-occupancy of one unit: 0% down for eligible veterans. Larger down payments reduce rates and improve DSCR ratio — putting 25% or more down at DSCR closing typically unlocks the most competitive pricing.
For conventional loans: yes, but typically only 75% of documented lease income is counted toward qualifying income, and you’ll still need to meet DTI requirements based on personal income. For DSCR loans: the property’s rental income is the entire basis for qualification — no personal income verification required. This distinction is what makes DSCR the preferred tool for investors whose personal income is complex, irregular, or already maxed on DTI from existing mortgage obligations.
With Fannie Mae conventional loans: maximum 10 financed properties per borrower. With DSCR loans: no limit. Portfolio and blanket loans: no limit. This means serious portfolio builders almost inevitably transition from conventional to DSCR as they scale beyond 10 properties. Planning that transition before you hit the wall is part of a good financing strategy.
Yes, through DSCR lending. No tax returns, no W-2s, no employment verification, and no DTI analysis are required. Qualification is based entirely on the property’s rental income relative to its debt service. This makes DSCR the primary financing tool for self-employed investors, business owners, and professionals with complex income structures.
Conventional investment loans typically require 680+ (with 740+ for best rates). DSCR loans: minimum 640 (some programs accept 600; 720+ for best pricing). FHA: 580 for 3.5% down; 500–579 for 10% down. VA: no set minimum but lenders typically prefer 620+. Higher credit scores translate directly to lower rates across all loan types — the difference between a 680 and a 740 FICO can mean 0.25–0.75% in rate, which adds up significantly on a 30-year hold.
There is no universal “best” — it depends on your income profile, property type, and portfolio size. W-2 employees with fewer than 10 properties and clean financial documentation often get the best rates with conventional. Self-employed investors, those with complex income, LLC-focused portfolios, or investors beyond 10 financed properties should prioritize DSCR. Veterans with eligible benefits should explore VA multifamily for their first acquisition. Equity-rich existing landlords should evaluate HELOC or cash-out DSCR refinance to scale without fresh capital.
DSCR loans fully support LLC and entity ownership — many investors prefer this structure for liability protection and to keep investment debt off personal credit reports. Conventional loans generally require individual vesting. If LLC ownership is a priority, DSCR is typically the right product. Consult a Maryland attorney on the specific liability and tax implications of LLC structuring for rental properties in your target county.
For DSCR qualification, income projections must reflect stabilized rents where applicable. In Montgomery County, the 5.7% cap for 2025–2026 means you cannot project rents above that annual increase rate for existing stabilized units. Prince George’s pre-2000 PRSA-subject units carry similar constraints. For properties built after 2000, or in counties with no stabilization (Anne Arundel, Frederick), rental income projections can reflect full market rates — a meaningful qualification advantage. Always confirm whether a specific property is subject to local rent regulations before building your DSCR qualification model.
A 1031 exchange allows you to sell one investment property and reinvest the proceeds in a new “like-kind” property, deferring capital gains tax on the sale. Maryland investors who purchased in strong appreciation markets years ago may have significant unrealized gains that would be heavily taxed in a straight sale. A 1031 exchange preserves that equity for reinvestment — allowing you to trade up to a larger or better-positioned asset while deferring the tax bill. The exchange must be completed through a Qualified Intermediary, with the replacement property identified within 45 days and closed within 180 days of the sale.
Still have a question?
CTA — Build Your Maryland Rental Investment Financing Plan Today
Financing clarity before you buy is the foundation of a profitable rental portfolio. Fortune Homes MD walks you through every option — for your situation, your market, and your long-term goals.
📞 Call Us: [Phone Number] 📧 Email: [Email] → Schedule Your Free Rental Investment Financing Consultation →
We serve investors across all major Maryland markets — Baltimore County, Montgomery County, Howard County, Prince George’s County, Anne Arundel County, Frederick County, and Baltimore City.
Ready to Start Your Rental Investment Journey?
Reach out to Fortune Homes to discuss how we can help you achieve your investment goals. Our team is here to provide expert guidance and support every step of the way.